- 0
- 823 words
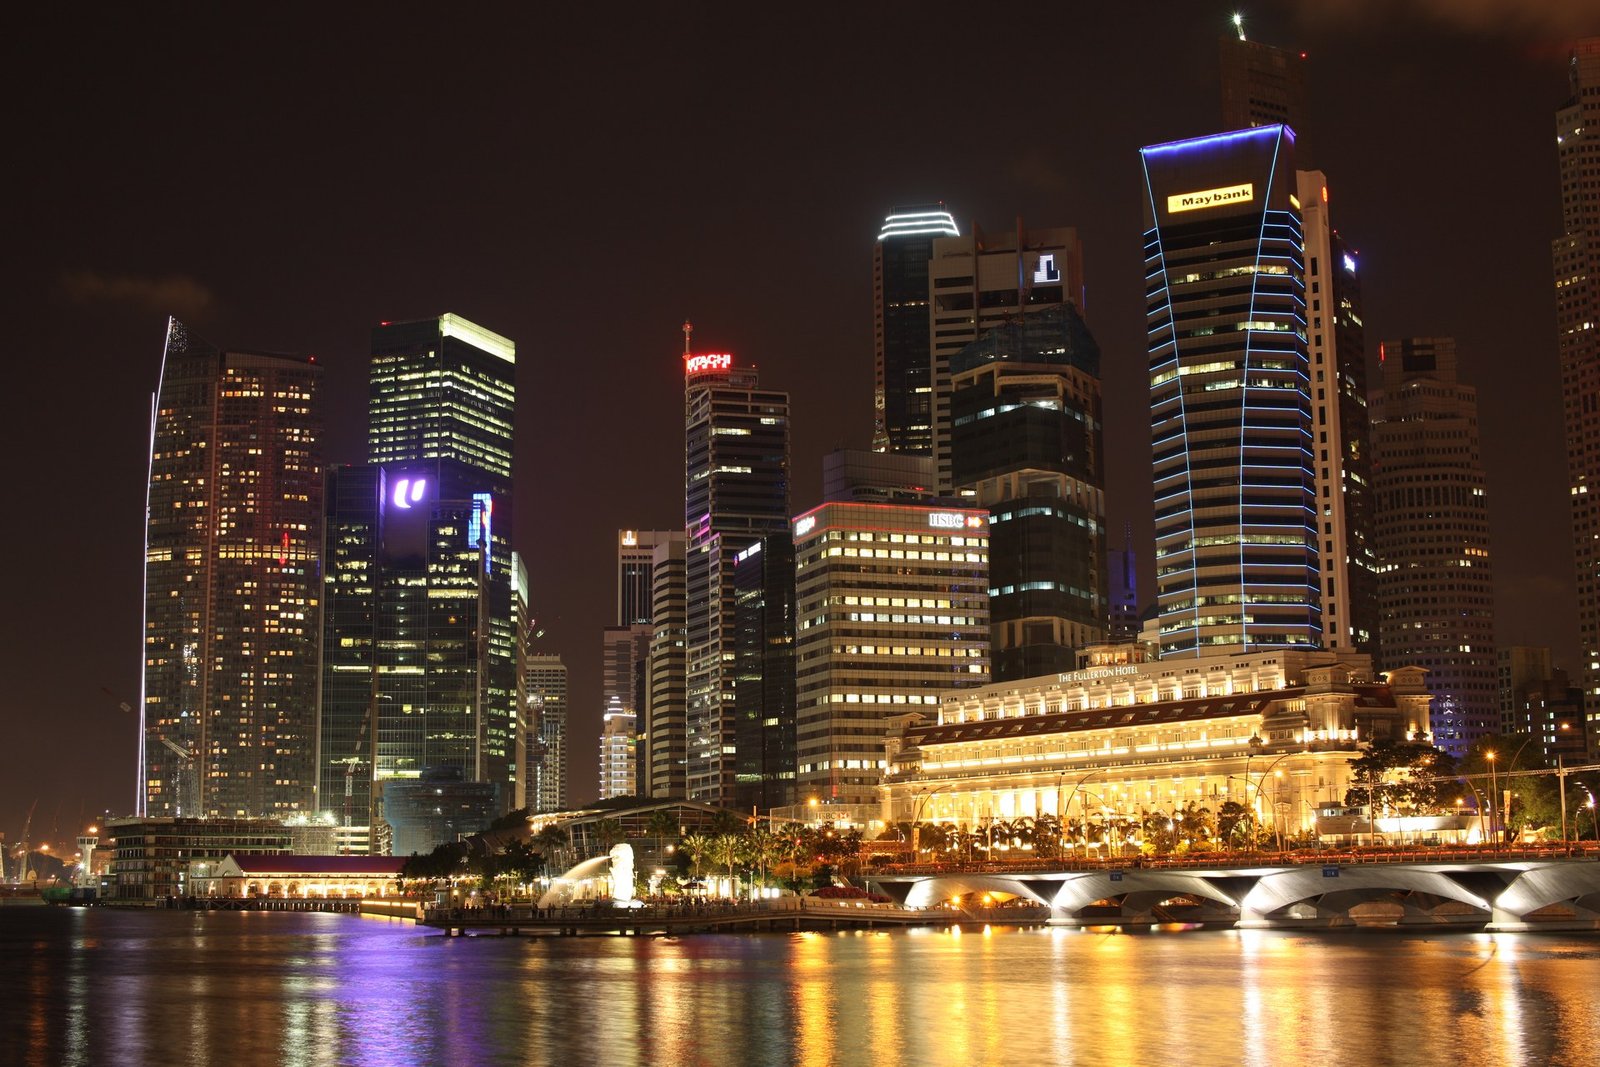
Asia’s technology-driven future looks brighter than Europe’s and competitive with the Americas because the region combines semiconductor manufacturing scale, mobile-first markets, young demographics in several large economies, and rising digital investment. Recent IMF, GSMA, UNCTAD and OECD findings support that outlook—even as trade tensions and digital divides remain real constraints.
Why is Asia’s technology outlook brighter?
Asia and the Pacific remains the world’s fastest-growing major region. The IMF’s October 2025 Regional Economic Outlook projects GDP growth of 4.5 percent in 2025 and 4.1 percent in 2026, after 4.6 percent in 2024—well above typical advanced-economy rates. First-half 2025 strength reflected exports and a buoyant tech cycle, while an AI-driven investment boom is cited as upside for economies deep in the tech supply chain.
How do mobile markets and demographics help Asia?
The GSMA’s Mobile Economy Asia Pacific 2025 estimates mobile technologies added about US$950 billion to regional GDP in 2024 (5.6 percent of GDP), with a path toward roughly US$1.4 trillion, or 6.6 percent of GDP, by 2030. About 1.5 billion people used mobile internet in 2024 (52 percent of the population), rising toward 1.8 billion (60 percent) by 2030. Five-G accounts for 18 percent of connections and could reach 50 percent by decade’s end.
Mobile-first behaviour shapes commerce from India and ASEAN to Korea and Gulf digital hubs. Younger profiles in South and Southeast Asia speed adoption; Japan and Korea lean on automation and AI to offset aging. Europe and North America are richer but more saturated; Asia still has room to grow usage.
Which sectors put Asia ahead?
Chips and AI hardware. Moody’s Ratings estimates Asia holds more than 75 percent of overall chipmaking capacity. SEMI data place China, Taiwan, Korea and Japan among the largest fab bases, with China, Taiwan and Korea together taking about 79 percent of global semiconductor equipment billings in 2025.
Digital investment. UNCTAD’s World Investment Report 2025 finds developing countries attracted about US$531 billion in announced greenfield digital-economy projects from 2020 to 2024, with more than 60 percent in six Asian economies: India, Malaysia, Indonesia, Singapore, Viet Nam and China. Asia also drew about US$190 billion in digital-equipment manufacturing announcements in that period.
Startups. The OECD’s Start-up Asia (2025) reports Asia absorbed 23 percent of global venture capital in 2021–23—second only to North America—and hosts about 19 percent of world startups, up from roughly an 8 percent VC share a decade earlier.
The United States still leads many software platforms and AI capital pools. Europe retains industrial strengths but, per the World Economic Forum’s 2025 assessment, competes effectively in only four of fourteen technologies critical to the future economy. Asia’s edge is manufacturing depth plus mass-market digital demand.
What could slow the rise?
Optimism needs balance. The IMF warns that tariffs may weigh on Asian exports. Chip geopolitics complicate advanced supply chains. GSMA notes nearly half of Asia Pacific remains offline. AI could widen gaps between large firms and SMEs, and uneven regulation will shape who scales. These risks temper Asia’s edge—they do not erase it.
Key highlights
- IMF (Oct 2025): Asia-Pacific growth ~4.5% in 2025 and ~4.1% in 2026, with tech-cycle strength and AI upside.
- GSMA: mobile sector ~US$950bn (5.6% of APAC GDP) in 2024; toward ~US$1.4tn (6.6%) by 2030.
- About 1.5bn mobile-internet users in 2024; 5G share seen rising from 18% to 50% of connections by 2030.
- Moody’s: Asia holds over 75% of chipmaking capacity; SEMI shows Asia-heavy fab and equipment leadership.
- UNCTAD WIR 2025: six Asian economies took >60% of developing-world digital greenfield projects (2020–24).
- OECD: Asia’s global VC share ~23% in 2021–23, up from ~8% a decade earlier.
- Risks: tariffs, chip geopolitics, offline populations, AI inequality and uneven regulation.
Conclusion
Asia’s technology future is bright relative to Europe and highly competitive with the Americas because chip and manufacturing scale meet mobile-first demand, young markets and accelerating digital investment. America’s platform leadership and Europe’s industrial know-how still matter. For the next decade, AI hardware ecosystems and specialisation across India, China, ASEAN, Korea, Japan and Gulf Asia give the region a distinctive runway—if networks stay affordable, skills stay inclusive and trade channels stay open.
FAQ
Why is Asia’s technology future considered bright?
Asia combines dense semiconductor manufacturing, fast-growing mobile economies and heavy digital greenfield investment. IMF projections still show regional growth well above advanced-economy averages, with AI-linked investment as an upside.
How does Asia compare with Europe and the US in tech?
The United States leads frontier software platforms and much AI capital. Europe has industrial strengths but lags in scale for several critical digital technologies. Asia’s edge is manufacturing depth, mobile-first mass markets and a rising startup/VC share.
Which Asian tech sectors are leading growth?
Semiconductors and AI hardware, mobile connectivity and digital services, electronics manufacturing, fintech and e-commerce, plus data-centre and clean-tech investment across India, China, ASEAN, Korea, Japan and parts of Gulf Asia.
What risks could hold Asia’s digital economy back?
Trade and tariff shocks, chip geopolitics, the large still-offline population, rising network costs, regulatory fragmentation, and inequality if AI gains concentrate in large firms. Inclusive policy can manage them without writing off Asia’s outlook.
Author

watannews321@gmail.com
Related Posts
Merz Vows to Keep Ruling Coalition Together for Germany’s ‘Democratic Future’
- 0
- 532 words
German Chancellor Friedrich Merz has vowed to keep his ruling coalition together for the sake of his country s democratic future, following...
Read out all
WMO: 2025 among driest river years in 35 years as land water storage keeps falling
- 0
- 568 words
WMO’s State of Global Water Resources 2025 finds below-normal flows across ~36% of basin area, a decade-long terrestrial storage decline, and a...
Read out all
Three South Korean Officers Wounded in Border Explosion
- 0
- 371 words
Three South Korean military officers were wounded in an explosion in the western sector of the Demilitarized Zone (DMZ) that separates North...
Read out all
German Chancellor Merz Defiant After CDU Suffers Double Election Blow
- 0
- 557 words
German Chancellor Friedrich Merz has called his party’s recent election loss in Mecklenburg-Vorpommern a ‘disaster’, but has vowed to remain in office...
Read out all
Trump’s Proposed Arch Near National Mall to Serve as Military Complex with Drones and Snipers
- 0
- 420 words
President Trump has proposed a military complex near the National Mall in Washington D.C. that would include snipers and drones. The project...
Read out all
Exploring the Latest Wellness Trends Among Youth in 2026
- 0
- 597 words
Introduction The world of wellness is constantly evolving, and the latest trends among youth in 2026 are no exception. As young people...
Read out all